Funding a First Home: A Parent’s Guide to Deposit Contributions
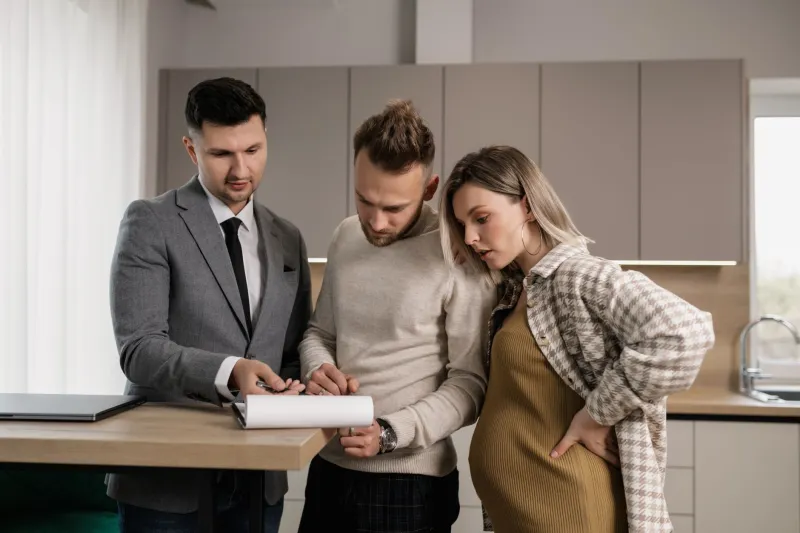
For many families in England and Wales, a parental contribution is now a normal part of buying a first home. The money may be offered with warmth and goodwill, but the legal consequences can be less straightforward. A transfer that feels like a family gift can look different if the buyer’s relationship ends, if a mortgage lender asks where the deposit came from, or if insolvency intervenes. The safest approach is not to distrust the arrangement. It is to record what everyone actually intends while everyone is on good terms.
Gift or loan? The label is not the whole answer
A gift is money given outright. The buyer is not expected to repay it, and the parent does not usually acquire a share in the property. A loan creates a debt. The buyer is expected to repay the money, whether on a fixed date, on sale of the property, or on demand. The law looks at the reality of the arrangement and the evidence surrounding it, not simply at the word used in conversation.
If there is an understanding that the money will be repaid, it is safer to treat it as a loan from the outset. If there is no expectation of repayment, a short gift letter can prevent confusion later. Ambiguity is the enemy. A vague arrangement may be interpreted differently by a mortgage lender, a court, an trustee in bankruptcy, or a surviving family member.
Why the distinction matters
Mortgage lenders are concerned with source of funds and affordability. They often require a gifted deposit letter confirming that the money is a gift and does not need to be repaid. If parents have actually agreed a loan but describe it as a gift, that can amount to a misrepresentation. A loan may also affect how the lender assesses the buyer’s finances, and some lenders will require consent or impose conditions.
The distinction matters in other contexts too. If the buyer becomes insolvent, a documented loan may allow the parent to prove as a creditor, although recovery will usually depend on the borrower’s assets and the parent’s security position. A gift is generally not repayable. If the buyer and their partner separate, a declaration of trust or loan agreement may help to show what was intended. If other children later ask whether the arrangement was fair, a written record can explain the reasoning.
If the money is a gift
A gift letter should be simple and accurate. It should identify the donor, the buyer, the amount, and the property purchase. It should confirm that the money is a gift, that it is not repayable, that no interest is payable, and that the donor does not expect to acquire an interest in the property. Parents should not sign a lender’s standard letter if it does not reflect the true arrangement.
Keep bank records showing the transfer. If the property is being bought by a couple, a declaration of trust can state whether the parental contribution is a gift to one buyer, a gift to both, or something else. This is particularly important for unmarried cohabitants, because the law does not assume that they own the property equally simply because they live there.
If the parents actually want a share of the property or a return linked to its value, that is a different arrangement and needs specific advice. A simple gift letter would be the wrong document.
If the money is a loan
A loan agreement does not need to be lengthy, but it should be clear. It should record the amount, the date, the parties, the repayment terms, whether interest applies, and what happens if the buyer defaults. It should say when the loan becomes repayable: for example, on sale of the property, after a fixed number of years, or on demand. It should also say whether anyone else, such as the buyer’s partner, is liable for repayment.
Parents may wish to consider whether the loan should be secured by a second charge over the property. That can strengthen their position, but it requires careful advice and usually the mortgage lender’s consent. Many residential lenders restrict second charges, so this should be explored before completion, not afterwards.
A loan agreement should also be consistent with what the mortgage lender has been told. If the lender has been told the money is a gift, a later loan agreement may create serious difficulties. The paperwork should tell one coherent story.
Declarations of trust and co-ownership
When two people buy a home together, they can hold the legal title as joint tenants or tenants in common. A declaration of trust records how the beneficial ownership is divided. It can be especially useful where one buyer has provided a larger deposit, including a parental contribution.
The declaration can state whether the parental money is a gift to one buyer, a loan to one or both buyers, or a contribution that gives the parents no interest in the property. It can also set out what should happen if the property is sold or if one owner wants to buy out the other. For married and civil partners, the court has wide powers on divorce or dissolution, but a declaration of trust and loan documents can still provide useful evidence of what the family intended.
If circumstances change
If the buyer’s relationship breaks down, the first question is often who owns what. For unmarried cohabitants, there is no automatic equal division. A declaration of trust, loan agreement, and records of contributions may be central. For married or civil partners, the court has a broad discretion, but documents can still show the source and purpose of the deposit.
If the buyer becomes insolvent, a trustee in bankruptcy may examine the property and the contributions to it. A properly documented loan may help the parent establish a debt, although it will not necessarily be repaid in full. A gift is unlikely to be recoverable simply because the buyer later struggles financially. This is one reason why parents should not describe a loan as a gift to smooth a mortgage application.
If other siblings later raise concerns about fairness, the answer is usually found in family conversations and estate planning rather than in property law alone. Parents are entitled to help one child more than another, but they should record why and consider how their wills and lifetime gifts fit together. Fairness does not always mean identical treatment.
A practical checklist
- Decide before the transfer whether the money is a gift or a loan.
- Put the arrangement in writing at the same time as the transfer.
- Use the mortgage lender’s gifted deposit letter only if it is accurate.
- For a loan, record the amount, repayment terms, interest, and default position.
- Consider a declaration of trust if the property is bought by more than one person.
- Tell the mortgage lender what it needs to know and comply with its requirements.
- Keep bank records and copies of all documents.
- Review the arrangement if the property is remortgaged, sold, or transferred.
- Consider the wider family position, including wills and other siblings.
A parental deposit contribution can be one of the most generous things a family does. A little paperwork at the start can protect the money, reduce uncertainty, and help preserve the relationship if circumstances later change. This article is general information, not legal advice. Davis Solicitors can advise on the documents and arrangements suitable for a particular family.